


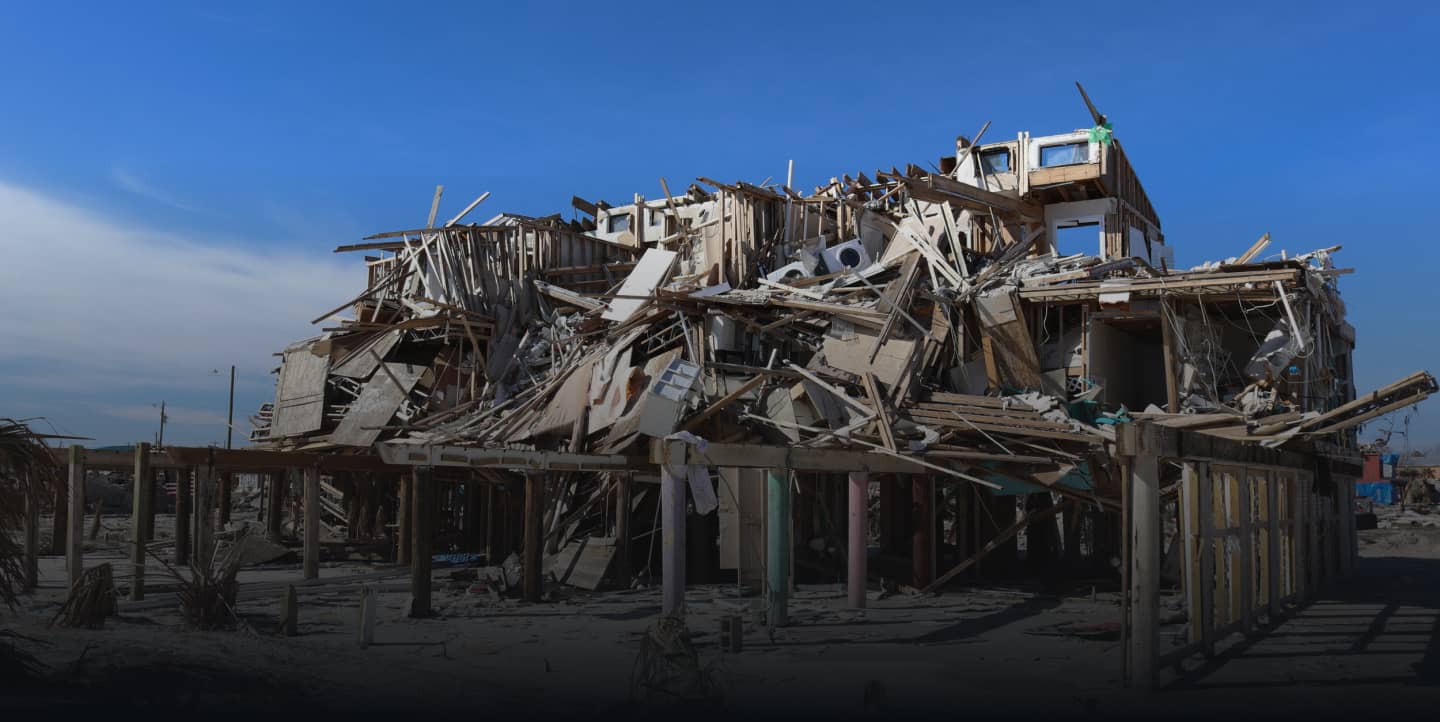
Hurricane Insurance Claims: How Larry Moskowitz, PA Helps Policyholders
Larry Moskowitz, PA is a property damage law firm that represents homeowners, business owners, and community associations in hurricane insurance claims. We work only for policyholders, never for insurance companies.
After a hurricane, many property owners find their claim denied, underpaid, or delayed. Our attorneys review the policy, document the damage, and push the insurance company to pay what the policy owes, including in court when needed.
Founding attorney Larry Moskowitz is licensed in Florida and Texas and has practiced law for more than 35 years. The firm handles property damage claims nationwide and has recovered millions of dollars for clients. Consultations are free, and if we don’t recover money for you, you owe nothing.

Understanding Hurricane Insurance Claims
What Does Hurricane Insurance Cover?
Coverage depends on your policy, but a standard Florida property policy typically includes:
- Wind damage to the roof, windows, doors, and walls
- Water damage inside the building when wind breaks an opening, such as a damaged roof or window
- Additional living expenses if your home can’t be lived in, or business interruption losses for commercial policies, when the policy includes them
Flood and storm surge damage is usually excluded and covered only by a separate flood policy. Insurers often blame damage on flooding to reduce what they pay, which is one of the most common disputes we handle.
How the hurricane deductible works: Florida policies have a separate hurricane deductible, usually $500 or 2%, 5%, or 10% of the home’s dwelling coverage. On a home insured for $300,000, a 2% deductible is $6,000. Under Florida law, the hurricane deductible generally applies once per calendar year when you stay with the same insurer.
Storms We’ve Helped Clients With
Our attorneys have represented homeowners, business owners, and community associations with insurance claims from these hurricanes:
Hurricane Isaias (2026): Category 2, near Destin, FL
Hurricane Milton (2024): Category 3, Siesta Key, FL
Hurricane Helene (2024): Category 4, Florida’s Big Bend
Hurricane Debby (2024): Category 1, Steinhatchee, FL
Hurricane Beryl (2024): Category 1, Matagorda, TX
Hurricane Ian (2022): Category 4, Cayo Costa, FL
Still dealing with a denied or underpaid claim from one of these storms? Contact us to review your options.
How Do I File a Hurricane Insurance Claim in Florida?
Report the damage to your insurance company as soon as possible, document everything before cleanup, and keep a record of every conversation. Here are the key steps:
- Make the property safe. Take reasonable steps to prevent more damage, like tarping a roof or boarding windows, and keep every receipt.
- Document the damage. Take photos and video of every room and the outside before anything is removed or repaired. List damaged items, and keep them if you can.
- Report the claim promptly. Florida law generally requires notice of a new claim within one year of the date of loss, and notice of a supplemental claim for additional damage within 18 months.
- Keep a claim file. Save your policy, your claim number, and notes on every call and email with the insurance company.
- Be there for the inspection. The insurer generally must inspect within 30 days after receiving your proof-of-loss statements. Ask for the adjuster’s estimate, which the insurer must send within 7 days after it’s created.
- Watch the 60-day deadline. The insurer generally must pay or deny your claim within 60 days after you give notice, unless delays are beyond its control.
- Talk to an attorney before you sign anything or cash a check marked “final.”
Why Are Hurricane Insurance Claims Denied or Underpaid?
After a major hurricane, insurance companies handle thousands of claims at once, and many policyholders receive less than their policy owes. The most common problems we see are:
- Wind vs. flood disputes. The insurer says water caused the damage, which a standard policy usually excludes, when wind actually broke the roof or windows first.
- Low estimates. The adjuster’s estimate leaves out damaged areas, uses low repair prices, or misses hidden damage like wet insulation and mold.
- “Wear and tear” or “pre-existing damage.” The insurer blames the damage on age or old problems rather than the storm.
- Deductible mistakes. The wrong deductible is applied, or the hurricane deductible is charged twice in the same year.
- Delays. Inspections, estimates, and payments drag on for months while repairs wait.
If your claim was denied, underpaid, or delayed, a property damage attorney can review your policy and the insurer’s decision, and push for the full amount the policy owes.
Legal Guidance with Larry Moskowitz, PA
Larry Moskowitz, PA represents policyholders whose hurricane claims have been denied, underpaid, or delayed. Our attorneys handle the claim from start to finish, so you can focus on recovering and rebuilding.
How Our Attorneys Help
- Policy review: We read your full policy and the insurer’s decision to find every coverage that applies.
- Damage evaluation: We work with independent experts, such as engineers and estimators, to document the true cost of repairs.
- Negotiation: We deal with the insurance company for you and push for the full amount owed.
- Litigation: If the insurer won’t pay fairly, we’re prepared to take your case to court.
What to Expect When You Hire Us
- Free case evaluation: Tell us what happened and share your policy and claim documents. There’s no cost and no obligation.
- Investigation: We review the claim, inspect the damage, and identify what the insurer missed or got wrong.
- Demand and negotiation: We present the full value of your claim and negotiate with the insurance company.
- Resolution: Most claims settle. If yours doesn’t, we’re ready to file suit. If we don’t recover money for you, you owe nothing.


